NPS, UPS, EPF & EPS, APY, SCSS & Annuities — your corpus, decoded for 2026-27
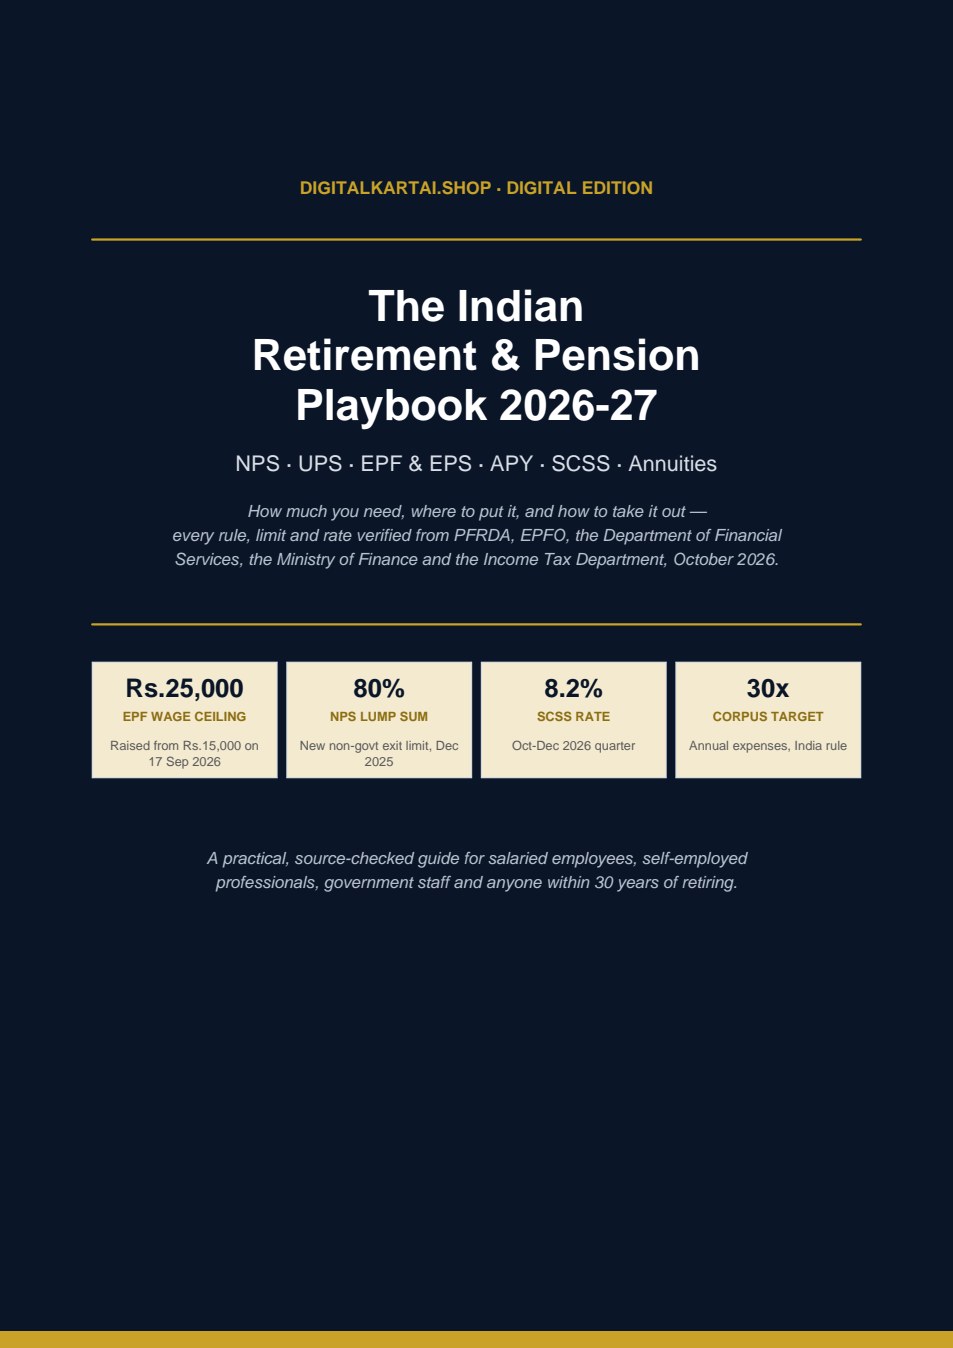
The complete 36-page playbook for building and drawing retirement income in India. How much you actually need, where to put it, and how to take it out — with the 2026 EPF ceiling hike to ₹25,000, the new NPS exit rules and equity categories, the Unified Pension Scheme, and the renumbered tax sections under the Income Tax Act, 2025. Every rule, limit and rate verified from PFRDA, EPFO, the Department of Financial Services and the Income Tax Department, October 2026.
Get Your Copy →Built for every Indian within thirty years of retiring
Understand your EPF and EPS, the new ₹25,000 wage ceiling, the higher-pension option, and how much more you must save on top.
No employer match, no automatic pension — a full chapter on manufacturing your own retirement with NPS, PPF and mutual funds.
The NPS-versus-UPS decision explained clearly, with contribution rates, assured payouts and the 8th Pay Commission context.
The 30x rule, the SIP maths, and why starting five years earlier can halve what you must invest every month.
Six things most retirement guides get wrong in 2026
The 30x rule for India, worked with real tables — and why the imported 25x rule quietly underfunds retirement.
Tier I and II, the Multiple Scheme Framework, the new A–E equity categories, 100%-equity options and the eased exit rules.
The ₹25,000 ceiling, the pension formula, the ₹1,000 floor, the higher-pension joint option and the 2026 court rulings.
Deductions and exit tax under the Income Tax Act, 2025 — Sections 123 and 124, and the 80% withdrawal / 60% exemption gap.
SCSS at 8.2%, POMIS, PPF, NSC and annuities — what they pay, who they suit, and the PMVVY trap to avoid.
Age-wise model portfolios, a 12-month action plan, a readiness checklist and the nine mistakes that cost lakhs.
Ten parts — from the 2026 pension reset to the last mile before retirement
The five changes in eighteen months that moved the goalposts, and what each means for you by age.
The 30x rule, your target corpus worked with real numbers, and the monthly-investment maths.
Contributions, the new ₹25,000 ceiling, the pension formula, the higher-pension option and EDLI cover.
Tiers, investment choices, the A–E categories, costs, partial withdrawal and the complete exit table.
What UPS promises, how the contributions differ, and a clean NPS-versus-UPS comparison.
A guaranteed pension floor, with the full age-wise contribution table and honest limitations.
SCSS, POMIS, NSC, KVP, PPF, annuities and your health fund — the instruments that turn a corpus into income.
Deductions at entry, tax at exit, the annuity wrinkle, and the renumbered sections under the 2025 Act.
Model portfolios by age, a 12-month action plan, common mistakes and the questions people ask most.
Self-employed plans, the five years before retirement, sequence-of-returns risk, the women's retirement gap and paperwork.
One-time payment · Lifetime access · No subscriptions
Your purchase is protected
Your download link is ready the second your payment succeeds.
Corrupted or incomplete file? We replace it within 24 hours — no questions asked.
UPI, cards, net banking & wallets — processed on PCI-DSS compliant infrastructure.
Everything you need to know before buying
Anyone in India who is saving for retirement or about to start drawing it — salaried employees, self-employed professionals, government staff and people within thirty years of retiring. It assumes no prior knowledge of pensions or tax.
Yes. Every rule, rate and date is taken from official sources current to October 2026 — including the EPF wage-ceiling increase to ₹25,000 (17 September 2026), the NPS exit reforms of December 2025, the Multiple Scheme Framework and the August 2026 equity-classification circular, and the renumbered sections of the Income Tax Act, 2025.
It covers NPS in full (Tier I and Tier II, investment choices, costs, withdrawal and exit), the Unified Pension Scheme for central government employees, EPF and EPS for salaried workers, Atal Pension Yojana for the unorganised sector, and the guaranteed-income instruments retirees use — SCSS, POMIS, PPF, NSC and annuities.
It gives you the method and worked tables. You project your expenses, multiply by the 30x factor, subtract what you will already hold, and solve for the monthly amount — with a worked example and age-wise tables to follow. It is educational, not personalised advice.
After successful payment on Razorpay, you are automatically redirected to a thank-you page with a download button. Click it to get your PDF instantly — it is yours forever.
Digital products are non-refundable because they are instantly downloadable. But if you receive a defective or corrupted file, or were charged incorrectly, we will replace or resolve it — just email lonefaisal977@gmail.com within 7 days.
No. The playbook is educational and explains schemes, rules and maths in general terms. Before committing money to any product, or making a withdrawal, please consult a SEBI-registered investment adviser and, for tax, a qualified chartered accountant.
Email us at lonefaisal977@gmail.com or message us on WhatsApp at +91 96826 00301. We typically respond within 24 hours.
Readers of this playbook usually pair it with one of these
How to actually run the equity SIP that funds the corpus — funds, platforms, step-ups and rebalancing.
The full renumbered tax framework — the natural companion to Part 8 of this playbook.
Nominations, wills and succession — the paperwork that makes sure your retirement money reaches your family.
36 pages · 34 sections · 20 tables — start reading in 60 seconds.
Get Your Copy →